Southeast Asia Chip Price Index Q3 Strong Rebound: Thai Semiconductor Market Revival Opportunity
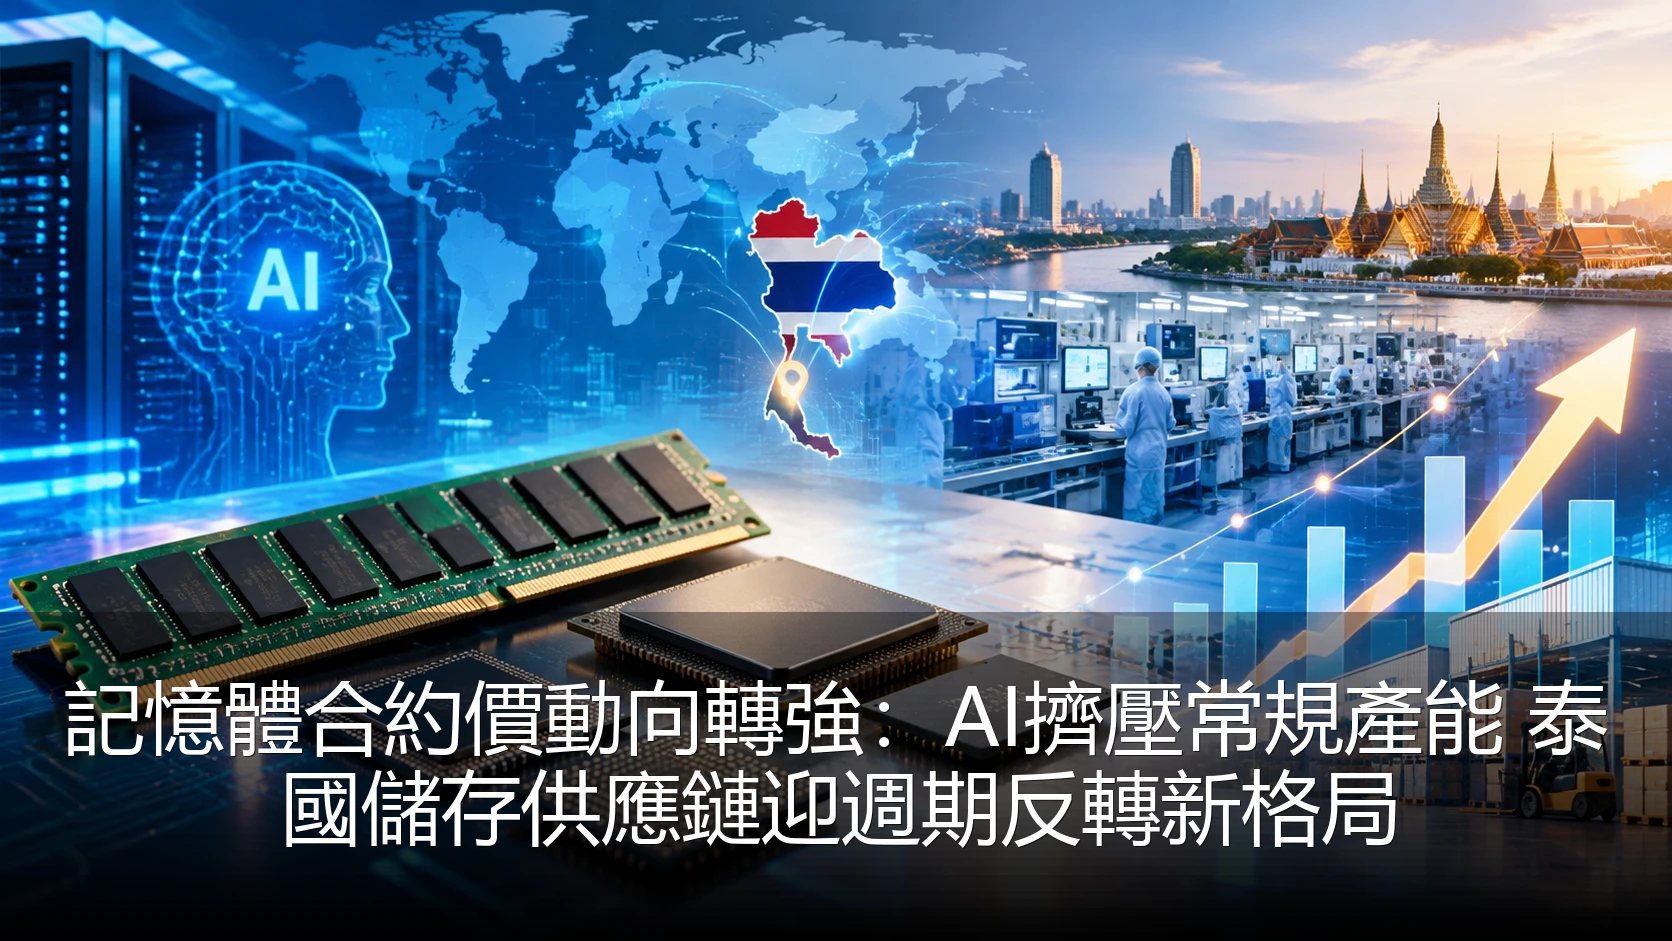
In Q3 2026, the Southeast Asia region's chip price index showed a strong rebound trend, marking the largest quarterly increase in nearly two years. As a regional semiconductor manufacturing center, the Thai market has become the biggest beneficiary of this price rebound thanks to its complete industrial chain layout and international cooperation network. According to the latest data, the Southeast Asia Chip Price Index increased by 12.7% in Q3 2026 compared to the previous quarter, with Thailand's region reaching a 15.3% increase, far exceeding the regional average. This trend not only marks the semiconductor market's official exit from the inventory adjustment cycle but also brings unprecedented development opportunities for Thailand's semiconductor industry.
Multiple Driving Factors Behind the Price Rebound
The strong rebound of the Southeast Asia Chip Price Index is not accidental but the result of multiple factors working together. First, the rapid development of the global AI industry has driven a surge in demand for high-performance computing chips. With the launch of new-generation AI models like ChatGPT-5 and Gemini Ultra, demand for GPUs and specialized ASIC chips has shown explosive growth. According to market research data, global AI chip shipments in Q3 2026 increased by 78% compared to the same period last year. As an important global packaging and testing base, the Southeast Asia region has undertaken a large number of AI chip packaging and testing orders, directly driving up the prices of related chips.
Second, the recovery of the automotive semiconductor market has become another important driving force. With the acceleration of global automotive electronics and intelligence trends, demand for automotive MCUs, power semiconductors, and sensors continues to grow. Especially against the backdrop of the rapid expansion of the electric vehicle market, the supply of automotive power semiconductors and IGBT modules remains tight. As the largest automotive manufacturing base in the ASEAN region, Thailand has abundant application scenarios for automotive semiconductors. In this price rebound, automotive chip prices increased by 18.5%, becoming an important force driving the overall index upward.
End of Inventory Adjustment Cycle, Supply-Demand Balance Achieved
In the first half of 2026, the global semiconductor industry experienced continuous inventory adjustments, leading to chip prices being in a downward channel for a long time. However, entering the third quarter, inventory levels have fallen to a healthy range, and inventory turnover rates across the supply chain have significantly improved. According to industry statistics, global semiconductor inventory days in Q3 2026 decreased from 76 days in the previous quarter to 65 days, close to the historical average of 58 days, indicating that the inventory adjustment cycle is nearing its end.
At the same time, wafer foundry quotations in Q3 also showed a trend of stopping the decline and rebounding. Wafer foundry quotations for advanced process nodes (7nm and below) increased by 5-8%, while quotations for mature processes (28nm and above) increased by 3-6%. This trend reflects that after a long period of capacity expansion, wafer foundries are beginning to focus more on the balance between capacity utilization and profitability, optimizing capacity allocation through pricing strategies.
Unique Advantages of the Thai Semiconductor Market
Against the backdrop of the overall increase in the Southeast Asia Chip Price Index, the Thai semiconductor market has shown particularly outstanding performance, mainly due to its unique industrial advantages and policy support. First, Thailand has a complete semiconductor industry chain layout, with presence in all aspects from wafer manufacturing, packaging and testing to application design. Especially in the packaging and testing field, Thailand has developed into the world's third largest packaging and testing base, with production bases of more than 20 international top packaging and testing enterprises, including industry leaders like ASE Technology Holding, Chantech, and KYE Systems.
Second, the Thai government continues to introduce preferential policies to support the development of the semiconductor industry. In August 2026, Thailand's Board of Investment (BOI) announced a new semiconductor investment incentive plan, offering up to 8 years of corporate income tax exemptions for investment projects in advanced packaging and testing, power semiconductors, and automotive chips, as well as tariff exemptions for imported equipment and raw materials. These policy measures have greatly enhanced Thailand's attractiveness to international semiconductor companies.
Capacity Expansion and Technology Upgrade Advancing Together
Facing rapid market demand growth, Thai semiconductor companies are actively expanding capacity. In Q3 2026, Thailand's semiconductor manufacturing capacity utilization reached 92.3%, an increase of 5.7 percentage points from the previous quarter, reaching a high in nearly two years. Several international semiconductor companies have announced expanded investments in Thailand, including TSMC's announcement to build a new advanced packaging plant near Bangkok with an investment of up to $1.5 billion; Intel also announced the expansion of its testing center in Thailand, specifically providing testing services for AI chips.
In terms of technology upgrades, Thailand's semiconductor industry has also made significant progress. In September 2026, Thailand's first domestically developed 5G communication chip was successfully put into production, marking an important breakthrough for Thailand in the chip design field. At the same time, Thailand has cooperated with ASEAN countries such as Singapore and Malaysia to establish a regional semiconductor R&D center, jointly promoting the research and application of advanced packaging and testing technologies and power semiconductor technologies.
Investment Opportunities Brought by the Price Rebound
The strong rebound of the Southeast Asia Chip Price Index has brought multi-dimensional investment opportunities for investors. First, in the upstream of the industry chain, wafer material and equipment suppliers will directly benefit from the demand growth brought by capacity expansion. According to market analysis, Thailand's wafer material market size is expected to reach $2.8 billion in the second half of 2026, with an annual growth rate exceeding 20%. Second, in the midstream of the industry chain, wafer foundries and packaging and testing companies will achieve higher capacity utilization and profit margins, especially companies with advanced packaging and testing technology will gain a competitive advantage in the AI chip packaging and testing field.
For investors, here are several investment directions worth paying attention to:
- AI Chip Packaging and Testing Companies: With the surge in AI computing power demand, companies focusing on high-performance computing chip packaging and testing will enter a period of high performance growth. Thailand's packaging and testing companies, with their technical advantages and capacity scale, are expected to become an important base for global AI chip packaging and testing.
- Automotive Semiconductor Suppliers: The rapid expansion of the electric vehicle market has driven the growth of demand for automotive power semiconductors and MCUs. As a global automotive manufacturing center, related suppliers in Thailand will directly benefit from the growth of local market demand.
- Advanced Process Equipment Suppliers: With the technological upgrading of Thailand's semiconductor industry, demand for advanced process equipment will continue to grow. Equipment suppliers, especially those for advanced packaging and testing equipment and power semiconductor manufacturing equipment, will gain development opportunities.
- Local Semiconductor Material Companies: The Thai government is actively promoting the localization of semiconductor materials, and local material companies will grow rapidly with policy support, with clear import substitution opportunities.
Risk Warnings and Response Strategies
Although the market outlook is positive, investors still need to pay attention to potential risks. First, global economic uncertainty may affect consumer electronics and automotive market demand, thereby indirectly affecting the semiconductor market. Second, geopolitical risks may lead to supply chain restructuring, impacting the semiconductor industry. Finally, technological progress and capacity expansion may lead to medium-term oversupply, causing price fluctuations.
In response to these risks, investors are advised to adopt the following strategies:
- Focus on company fundamentals, selecting high-quality companies with leading technology, high capacity utilization, and diversified customer structure
- Diversify investments, avoiding excessive concentration in a particular segment or type of company
- Hold long-term positions, avoiding excessive influence of short-term price fluctuations on investment decisions
- Closely monitor policy changes and industry trends, flexibly adjusting investment portfolios
Future Outlook: The Golden Age of the Thai Semiconductor Market
Looking ahead to the second half of 2026 and 2027, Thailand's semiconductor market is expected to enter a golden development period. On one hand, the dual-driven demand from AI and electric vehicles will continue to drive semiconductor market growth; on the other hand, Thailand's continuous policy support and industrial upgrading will further consolidate its position as a regional semiconductor manufacturing center.
According to the latest forecast from WSTS (World Semiconductor Trade Statistics), the global semiconductor market size will reach $620 billion in 2026, with an annual growth rate of 8.3%, of which the Southeast Asia region's growth rate will reach 12.5%, far exceeding the global average. With its unique industrial advantages and policy support, Thailand is expected to achieve growth of over 15%, becoming one of the main driving forces for the global semiconductor market growth.
Overall, the strong rebound of the Southeast Asia Chip Price Index in Q3 is not only a natural market cycle rebound but also an important signal for the beginning of a new semiconductor industry cycle. For the Thai semiconductor market, this price rebound has not only brought short-term performance growth but also laid a solid foundation for long-term industrial upgrading and international cooperation. For investors, grasping the development trend of Thailand's semiconductor market will yield substantial investment returns in the coming years.
Under the trend of parallel globalization and regionalization, Thailand's semiconductor industry is facing a historic development opportunity. Whether it's companies at all links of the industry chain or investors seeking high returns, they should all pay attention to the potential of Thailand's semiconductor market, seize the development opportunities brought by this price rebound, and jointly welcome the golden age of Thailand's semiconductor market.